My GC Requires Primary and Noncontributory Insurance. What Does That Mean?
Your COI comes back from the general contractor's compliance team with a note: "General Liability must be primary and noncontributory in favor of the GC and owner. Provide endorsement." Your crew is scheduled to start Monday.
Here is what it means. The GC wants your General Liability policy to respond first to a covered claim involving them, ahead of their own insurance. They also want your insurer not to ask their insurer to share the cost. That arrangement only exists if your policy actually says so, usually through an endorsement, and only for claims your policy covers. The contract sets the requirement. Your policy language decides whether you meet it.
What Does Primary and Noncontributory Mean?
The phrase has two parts.
- Primary means your policy is intended to respond before the GC's other insurance when a covered claim involves the GC as an additional insured on your policy.
- Noncontributory means your insurer is not supposed to go to the GC's insurer and ask it to split the loss, where the clause applies.
Here is a simple example. You are an HVAC subcontractor on a commercial remodel in San Jose. A visitor trips over a line set your crew left across a walkway and sues both you and the GC. If the GC is an additional insured on your policy and your policy has qualifying primary and noncontributory wording, your insurer would generally handle the GC's defense and covered damages first, without asking the GC's insurer to contribute.
The words to keep in mind are
covered and
applicable. Primary and noncontributory wording does not create coverage for claims your policy excludes, and it does not mean the GC's insurer will never pay anything on any claim.
Why Would My General Contractor Require This?
It is about how risk is divided on the project. On a typical job, both the GC and every sub carry liability insurance. When a claim comes out of a sub's work, the GC does not want its own policy taking the hit, paying a deductible, or showing a loss that affects its future premiums.
So the GC writes it into the subcontract: subs must name the GC (and often the owner) as additional insureds, on a primary and noncontributory basis. The requirement comes from
your project's insurance exhibit or subcontract, not from a statewide California rule that applies to every contractor.
When the contract requires it and the proof is missing, approval can stall. California's Department of General Services, for example, notes that on state contracts, missing certificates or endorsements can delay authorization to begin work. Private GCs and compliance portals often hold up mobilization for the same reason, though each contract sets its own process.
Is This the Same as Being an Additional Insured?
No. These three requirements often show up together, but each one answers a different question.
| Additional insured | Primary and noncontributory | Waiver of subrogation | Key Example / When It Applies |
|---|---|---|---|
| Who may get certain protection under your policy | How your policy and theirs interact for that party | Whether your insurer can pursue them to recover what it paid | When a contract requires you to protect the GC against claims resulting from your work on site. |
| Usually created by an additional insured endorsement | Created by policy wording or an endorsement such as CG 20 01 | Created by a waiver endorsement or policy provision | Applies when a covered claim involves an additional insured and the contract specifies your policy responds first without asking theirs to contribute. |
The key point: primary and noncontributory wording only works for a party that is already an additional insured. For the full background, see our guides on certificate holder versus additional insured and waiver of subrogation requirements.
What Is a Primary and Noncontributory Endorsement (CG 20 01)?
A common way to meet this requirement on a Commercial General Liability policy is the Insurance Services Office (ISO) form CG 20 01, Primary and Noncontributory – Other Insurance Condition. It changes the "Other Insurance" section of the policy.
The standard ISO version applies only when two conditions are met:
- The additional insured is a named insured on its own policy (the other insurance your insurer would otherwise share with).
- You agreed in a written contract that your insurance would be primary and would not seek contribution from the additional insured's insurance.
CG 20 01 does
not make anyone an additional insured. That status still has to come from a separate additional insured endorsement. If the contract also requires primary and noncontributory protection after your work is finished, the additional insured coverage needs to extend to completed operations too.
Not every policy uses CG 20 01. Some carriers build primary and noncontributory wording into their own additional insured endorsements or blanket forms. Others use proprietary versions with different conditions. What matters is the actual form on your policy, not whether it has a particular number. If the GC names a specific form, check whether yours matches or whether they will accept an equivalent.
Does a Certificate of Insurance Prove Primary and Noncontributory Coverage?
No. A certificate of insurance is evidence that a policy exists. It does not grant rights or change what the policy covers. If your policy does not contain primary and noncontributory wording, typing those words into the COI's description box does not add it.
That is why many GCs and compliance portals now ask for
copies of the endorsements themselves, not just the certificate. Expect to provide both. If you need a refresher on other common reasons a certificate gets sent back, see
why a GC might reject your certificate.
What Should I Send My Broker?
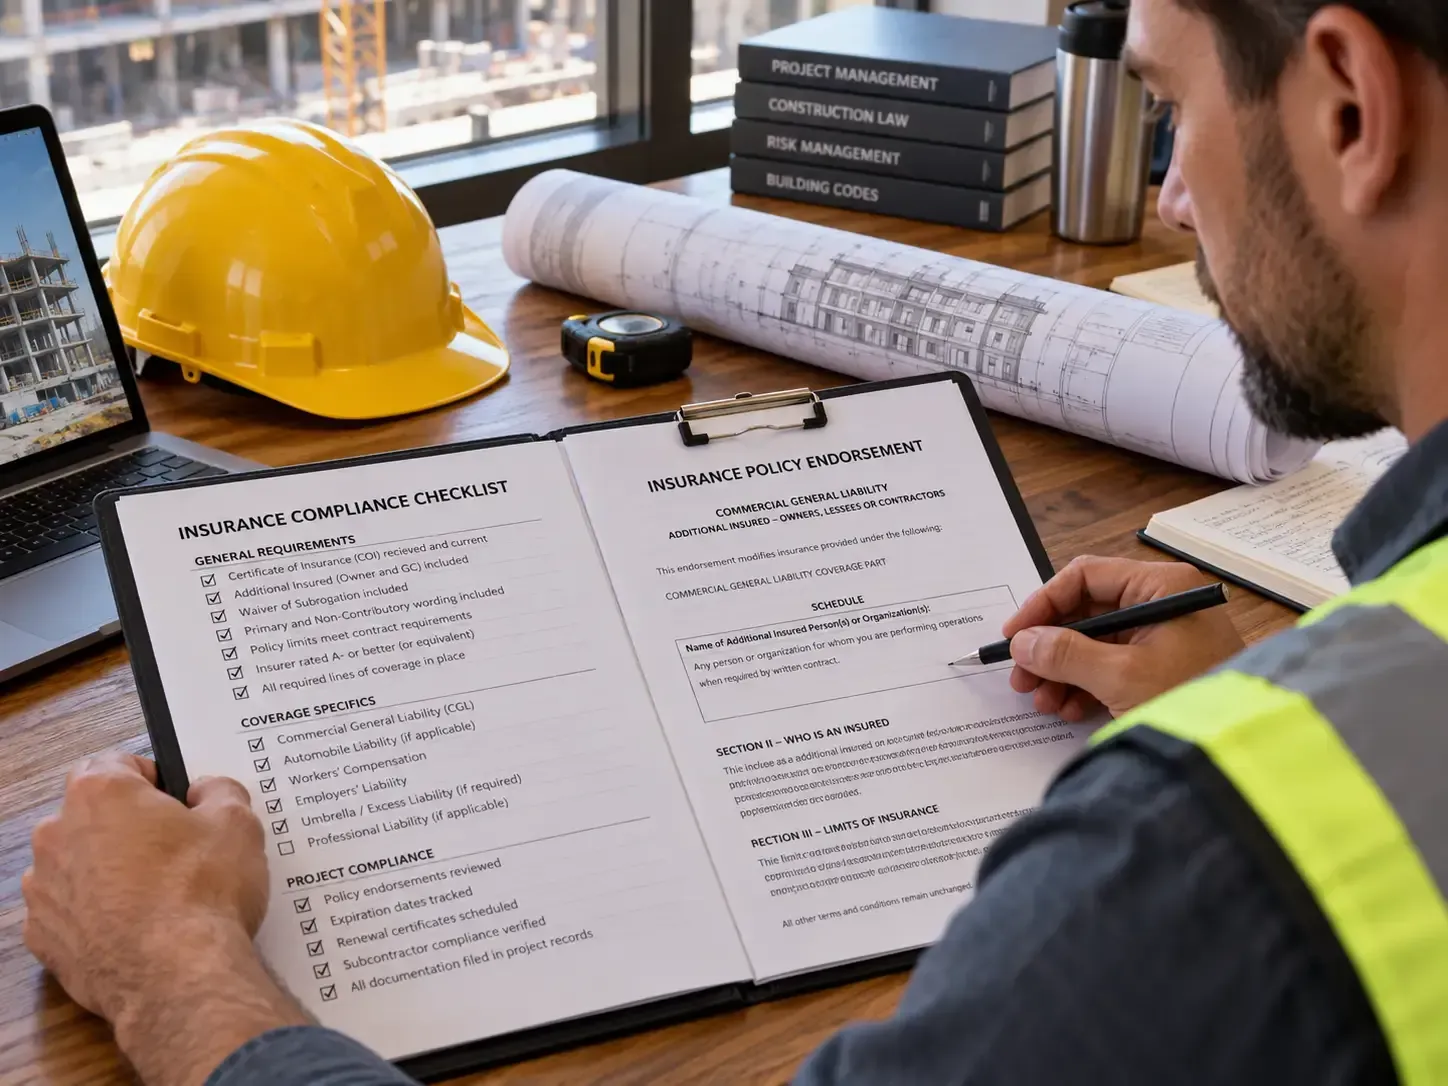
Give your broker everything in one email and you will usually get a clear answer faster. Send:
- The full insurance requirements exhibit and the subcontract pages that mention insurance
- The GC's or compliance portal's rejection message, word for word
- Any specific endorsement forms the GC named (for example, "CG 20 01" or "CG 20 10 and CG 20 37")
- The COI you already submitted
- Copies of your current policy endorsements, if you have them
- Full legal names of the GC, the owner, and any other parties listed
- Project name and address
- Your scope of work on the project
- Your mobilization date or submission deadline
Then ask your broker to confirm five things:
which policy the requirement applies to,
which parties need to be covered,
which work or operations must be included,
whether the written contract condition is met, and
exactly what documents the GC wants to see.
Your GC asked for primary and noncontributory coverage?
Send RVIS your insurance requirements and we will help you identify which endorsements need to be checked before your start date.
What If My Policy Does Not Have the Required Wording?
Your broker should first check whether your current policy already contains qualifying language. It may be built into an additional insured endorsement you already have.
If it does not, the broker can ask your carrier whether an endorsement can be added. Availability, timing, and any added premium depend on the carrier and your policy. Some carriers add it quickly. Others need underwriting review, and a few may not offer it on certain policies.
Costs, Timelines, Blanket vs. Scheduled Endorsements, and Non-Compliance
Adding a primary and noncontributory endorsement often incurs minimal cost or may even be included at no additional charge if your policy features a blanket endorsement. However, depending on your carrier and specific coverage terms, it can sometimes require an additional premium or underwriting approval.
Turnaround timelines vary: blanket endorsements can often be issued standard or within same-day turnaround, whereas custom or scheduled endorsements requiring carrier approval may take several business days.
Blanket vs. Scheduled Endorsements: A blanket endorsement automatically applies to any party you are obligated by written contract to list as primary and noncontributory. A scheduled endorsement specifically lists the entity name and project details directly on the policy form.
Failing to comply with these requirements can lead to serious consequences, including delayed start dates, withheld retainage or pay applications, or even breach of contract notices and potential removal from the job site.
If the wording is not available, talk with the GC early. They may accept an alternative, adjust the requirement, or give you time to resolve it. What you want to avoid is learning about the gap the day before mobilization.
Before You Mobilize: A Quick Verification Checklist
- Have you found the exact primary and noncontributory requirement in the contract?
- Are the correct parties (GC, owner, others) named or covered as additional insureds?
- Has your broker verified the actual primary and noncontributory wording on your policy?
- Have you attached the proof the GC asked for, including endorsement copies if required?
- Has the GC or compliance team confirmed your documents are approved?
If you can answer yes to all five, you are ready to get on the job.
How RVIS Can Help With Insurance Requirements
RVIS has worked with Bay Area contractors for more than 30 years, in English and Spanish. When a GC sends an insurance exhibit full of endorsement language, we can review what it asks for and compare it against your current California contractor general liability insurance. We will help you see what is already in place, what may need to be added, and what to send back to the GC.
Your GC Asked for Primary and Noncontributory Coverage?
Send RVIS the insurance requirements, your current certificate, and any rejection notes. We can review what the contract is asking for, help identify which endorsements need to be checked, and discuss available options before your project starts.
Review My Insurance Requirements
Frequently Asked Questions
Do I need primary and noncontributory wording on every job?
No. It is a contract requirement, not a universal legal one. Many commercial GCs and public agencies require it, while some smaller private jobs do not. Check the insurance section of each contract.
Can I have additional insured coverage without primary and noncontributory wording?
Yes. A party can be an additional insured on your policy without primary and noncontributory wording. In that case, how your policy and theirs share a loss depends on each policy's "other insurance" terms.
Is CG 20 01 always required?
No. CG 20 01 is a common ISO form, but carriers may meet the requirement through their own endorsements or blanket wording. Some contracts name CG 20 01 specifically. If yours does, ask your broker whether your form matches or whether the GC will accept an equivalent.
Can my broker just write the wording on my COI?
Writing "primary and noncontributory" on a certificate does not change your policy. A broker can note the wording on a COI when the policy actually includes it. If it does not, the wording has to be added by the insurer through an endorsement.
Is primary and noncontributory the same as a waiver of subrogation?
No. Primary and noncontributory deals with which policy responds first and whether insurers share a loss. A waiver of subrogation deals with whether your insurer can try to recover what it paid from another party. Contracts often require both.